
Nearly 60% of small business owners fail to secure favorable financing, often without understanding what went wrong. Tampa-based Lendavo provides those answers and a path to improvement.
Launched in May, the capital intelligence platform was developed to decode the opaque commercial lending process. By evaluating businesses through the lens of an underwriter, Lendavo aggregates over a dozen credit metrics to guide burgeoning entrepreneurs away from high-interest debt and toward viable funding.
“Business owners aren’t supposed to be experts in finance,” Lendavo CEO Ty Crandall told the Tampa Bay Reporter. “Most business owners, by default, end up in high-risk or high-cost financing because they don’t have time. They’re finding what’s available.”
Lendavo enters the market at a critical time for small business owners. Approximately 60% applied for or sought financing in the year preceding the most recent Federal Reserve Small Business Credit Survey.
However, 36% of small employers received just a portion of what they requested, and 29% were denied outright. Crandall blamed the 2008 financial crisis and subsequent legislation.
“Before the mortgage crisis … 90% of people who went out to get funding, got SBA (Small Business Administration) loans,” Crandall said. “After the Dodd-Frank Act changed things, where lenders kind of had more stringent requirements, then we saw this explosion of alternative lending in fintech.”
Many alternative lenders provide short-term, high-cost capital through merchant cash advance or revenue-based financing, Crandall said. Meanwhile, most small business owners are overwhelmed and “have no idea of the types of funding programs that exist.”
He noted that high-interest lenders have high profit margins and typically dominate online search optimization and advertising, which compounds the problem. Lendavo was developed to help the most vulnerable businesses, startups, pre-revenue companies and those generating less than $10,000 monthly, Crandall said.
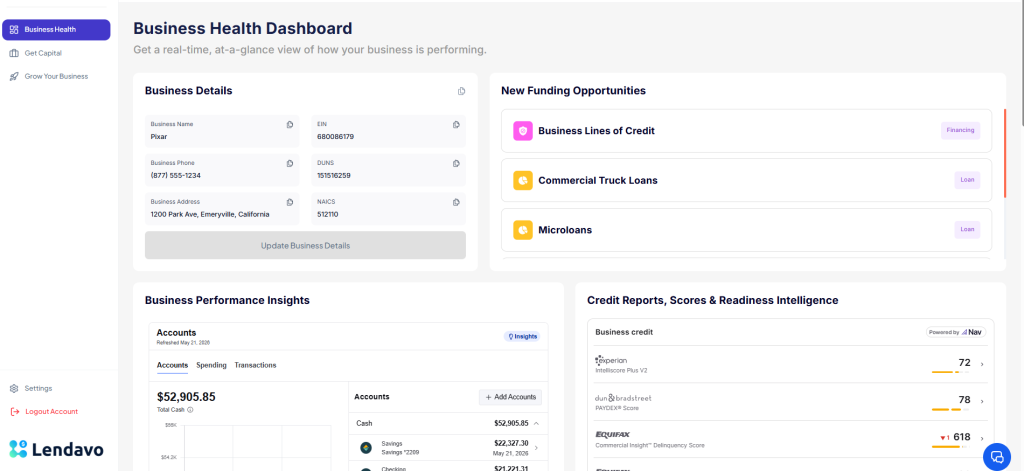
Users enter a business health dashboard after accessing the platform. The system aggregates 12 consumer and commercial credit scores, revenue data, projections and business valuations.
Lendavo relies on two proprietary metrics – a Funding Ready score and an SBA Readiness score. Rather than offering standard credit monitoring, these diagnostic tools identify why a business would face denial and provide a step-by-step roadmap to address deficiencies.
The platform also focuses on helping founders obtain financing without relying on personal guarantees or credit, insulating personal assets from business liabilities.
“We only monitor credit because we care what a lender sees about us, because that’s what matters when we apply,” Crandall explained. “The problem is that most monitoring out there doesn’t do that.
“The very first thing we do is help their borrower understand their business from a lender’s perspective.”
To prevent blind applications, Lendavo matches users with over 50 core funding programs across a network with more than 1,000 lenders. The platform details every variable for consideration, including interest rates, terms, required qualifications, necessary documents and closing times.
Crandall said a support team helps guide users, who receive a call “the minute they come on board,” through “every aspect” of the process. “What we find is that those who are even a little tech-savvy are using our tech to do the work.”
The automated, AI-driven platform also notifies users when their metrics change or a viable new funding source becomes available. “What Lendavo is designed to do is always give you a real-time view of the money you can get at any given time,” Crandall said.
He noted that the platform is also a business-to-business loss mitigation solution within the fintech sector. Commercial lenders pay for customer acquisition, despite only a small percentage of those leads qualifying for funding.
Lendavo can help mitigate those lost costs, Crandall said. “A lender’s job is to approve, not improve. It is just the default thinking that those are dead leads.”
Crandall said Lendavo is directly integrating with fintech lenders to change that industry standard. His company can help disapproved applicants rehabilitate their credit profile before rerouting them to their preferred financing source.
Commercial lenders are often shocked to hear his retention model, Crandall said. The industry has historically accepted low conversion rates as an unavoidable business cost.
That shifts the application dynamic from a definitive “no” to a constructive “not ready yet,” Crandall added. “We find it very welcome and a breath of fresh air.”